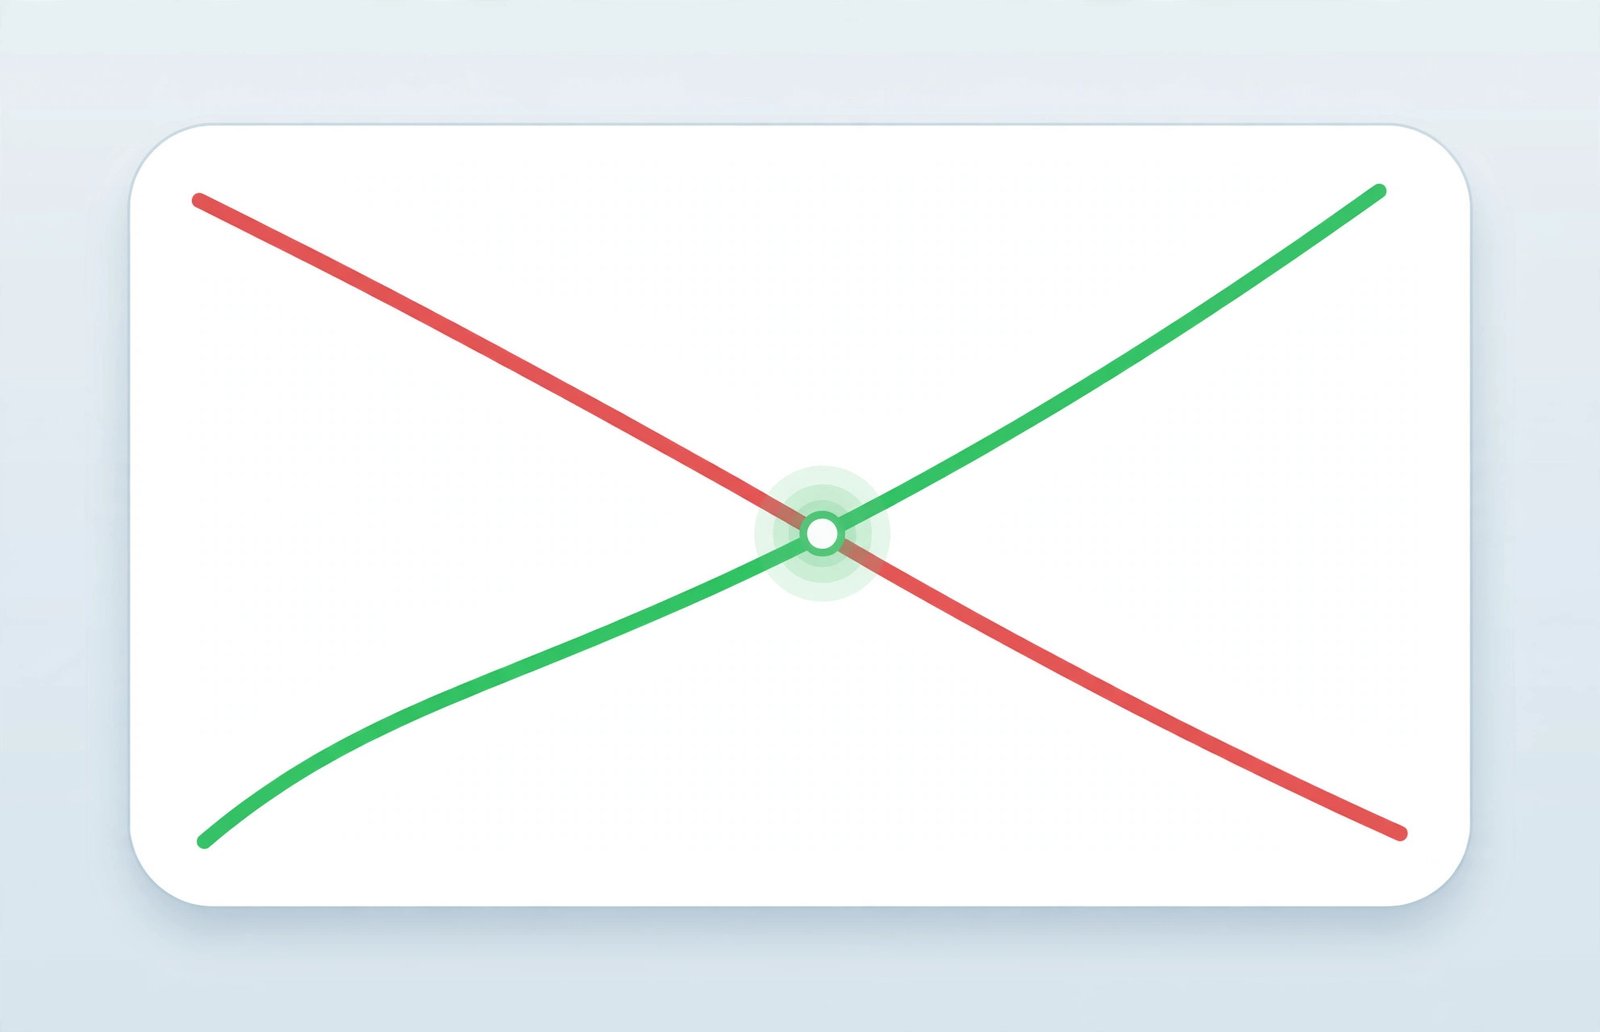
How Many Sales Before You Start Profiting?
Every business has a magic number: the sales volume where total revenue exactly covers total costs. Below it you lose money; above it every extra sale is profit. That number is the break-even point — and knowing it changes how you price, budget and plan.
This free calculator finds your break-even in both units and revenue, plus the contribution margin, profit at any volume you choose, and your margin of safety. Every step of the math is shown, and everything runs privately in your browser.
Units · revenue · profit at volume
Price must be above variable cost, and fixed costs can’t be negative.
Break-even point
Sell this many units to cover all costs
Assumes constant price and unit costs — real businesses face volume discounts, price pressure, and step-fixed costs (a second shift, a bigger space). Re-run the numbers whenever costs move. Educational math, not business advice.
How to Use This Calculator
- Enter your fixed costs — rent, salaries, insurance: everything that doesn’t change with volume.
- Enter price and variable cost per unit — what you charge, and what each unit costs to make or deliver.
- Optionally enter an actual or target sales volume to see profit and margin of safety.
- Click Calculate — read your break-even units, break-even revenue and full breakdown.
The Formulas
Break-even revenue = Break-even units × Price
Contribution margin = Price − Variable cost per unit (per-unit profit before fixed costs)
Worked example: fixed costs $10,000, price $50, variable cost $30. Contribution margin = $20. Break-even = $10,000 ÷ $20 = 500 units = $25,000 revenue. Sell 700 units and profit = 200 × $20 = $4,000.
Who This Helps
- Founders & small businesses setting prices and sales targets that actually cover costs.
- Product managers deciding whether a new line is worth launching.
- Freelancers figuring out how many clients or projects cover the month.
- Students learning cost-volume-profit analysis with the working shown.
Ways to lower your break-even
- Raise price — if the market allows, it’s the fastest lever.
- Cut variable costs — renegotiate suppliers, reduce waste.
- Trim fixed costs — every dollar of fixed cost removed lowers the bar permanently.
- Shift the mix toward higher-margin products.
Sales Needed for a Target Profit
Break-even tells you where profit starts — but plans are usually written the other way around: how much must we sell to make a target amount? The formula simply extends the numerator:
Using the example above — fixed costs $10,000, contribution margin $20 — a $5,000 monthly profit target needs ($10,000 + $5,000) ÷ $20 = 750 units, or $37,500 of revenue. If the division is not whole, round up: you cannot sell a fraction of a unit.
How the Levers Move the Number
| Change (from the example) | Contribution margin | Break-even units |
|---|---|---|
| Starting point ($50 price, $30 variable cost) | $20 | 500 |
| Price rises to $55 | $25 | 400 |
| Variable cost falls to $25 | $25 | 400 |
| Fixed costs rise to $12,000 | $20 | 600 |
Price is the most powerful lever here — every extra dollar of price lands entirely in the margin — which is why discounting is so corrosive: a $5 cut reverses the effect exactly.
Frequently Asked Questions
What is the break-even point?
The sales volume at which total revenue equals total costs — profit is exactly zero. Every unit sold beyond it contributes its contribution margin straight to profit.
What is contribution margin?
Price minus variable cost per unit: the amount each sale contributes toward covering fixed costs and then profit. A $50 product costing $30 to make has a $20 contribution margin.
What is margin of safety?
How far actual (or budgeted) sales sit above break-even, usually as a percentage. A 30% margin of safety means sales can fall 30% before losses begin.
Can a business break even with zero fixed costs?
Mathematically yes — break-even units would be zero, since every sale is immediately profitable. In practice, every real business has some fixed costs.
Does break-even analysis work for services?
Yes — treat billable hours or projects as “units,” your rate as the price, and contractor/freelancer costs as variable. The same formulas apply.
What are the limits of break-even analysis?
It assumes constant prices and unit costs, and a single product (or a stable mix). Real businesses face volume discounts, price elasticity and multi-product complexity — use it as a planning guide, not a guarantee.
How do I calculate the sales needed for a profit target?
Add your target profit to fixed costs, then divide by the contribution margin per unit: (Fixed costs + Target profit) ÷ (Price − Variable cost). With $10,000 of fixed costs, a $20 margin and a $5,000 target, that is 750 units. Always round the result up to the next whole unit.
Final Thoughts
Break-even analysis is the shortest path from “I hope this works” to “I know exactly what it takes.” Run your numbers, find your magic number, then price and plan with confidence.
Try our net worth calculator next.