Estimate your monthly car payment, total paid and total interest for any auto loan.
Results are estimates for planning purposes and are not financial, medical, or professional advice.
How to Use the Auto Loan Calculator
Small differences in rate or term can add thousands to the real price. This calculator works out the monthly payment, total paid, and total interest, so you can compare offers first.
- Work out the loan amount: price minus down payment and trade-in, plus rolled-in tax and fees.
- Enter the amount, the APR, and the term in years.
- Press Calculate for the monthly payment, number of payments, total paid, and total interest.
Auto Loan Calculator Formula
Auto loans use the amortizing loan formula. With P as the amount financed, r as the monthly rate (APR ÷ 100 ÷ 12), and n as the number of payments: M = P × r × (1 + r)^n ÷ ((1 + r)^n − 1). Total interest is M × n − P.
Example Calculation
A 35,000 dollar car with 5,000 dollars down leaves 30,000 dollars to finance at 7 percent APR for 60 months. The payment is 594.04 dollars; total paid is 35,642.16 dollars, including 5,642.16 dollars of interest. With the down payment added, the car costs about 40,642 dollars.
What to Enter as the Loan Amount
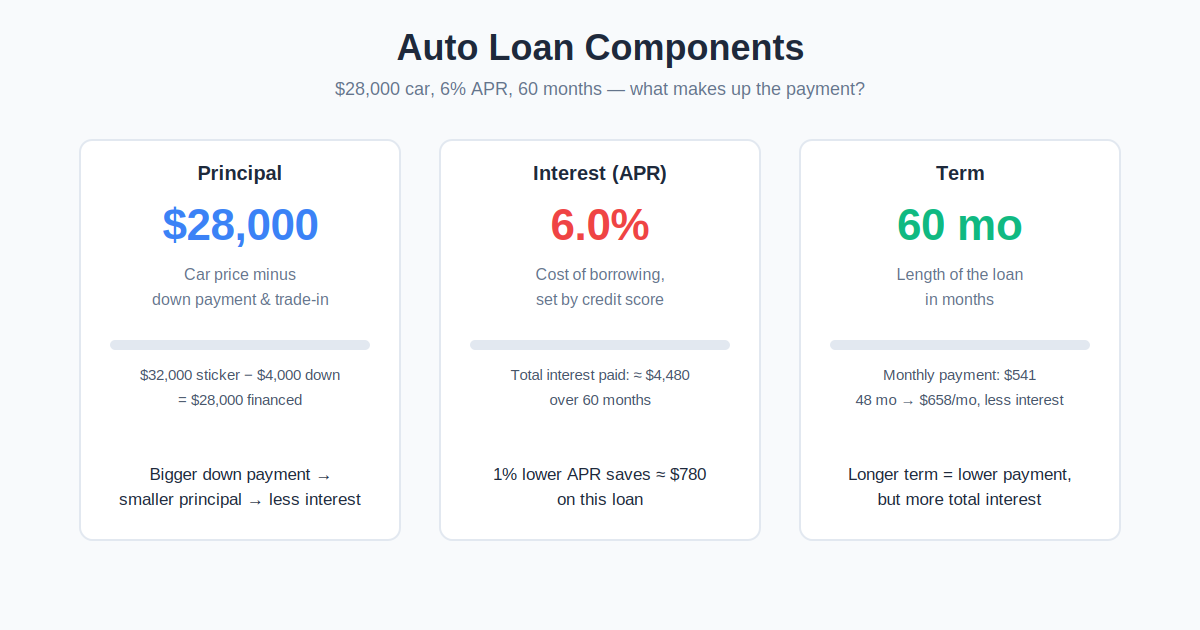
Enter the amount you borrow, which is rarely the sticker price: the price, minus your down payment and trade-in, plus sales tax and fees you plan to finance. In the example, 35,000 minus 5,000 down gives 30,000; entering the full price overstates every figure.
Comparing Loan Terms: 48, 60, and 72 Months
The same 30,000 dollar loan at 7 percent APR, changing only the term:
| Term | Monthly payment | Total interest | Total paid |
|---|---|---|---|
| 48 months | $718.39 | $4,482.59 | $34,482.59 |
| 60 months | $594.04 | $5,642.16 | $35,642.16 |
| 72 months | $511.47 | $6,825.85 | $36,825.85 |
Stretching from 48 to 72 months cuts the payment by about 207 dollars but adds about 2,343 dollars, and the balance falls slowly while the car loses value. Before signing, run the total past the 20/4/10 rule in the questions below.
Frequently Asked Questions
What is a good APR for an auto loan?
Rates depend on your credit score and the market: excellent credit can mean several points below average, while subprime borrowers pay far more. Compare several offers.
Should I choose a longer term for a lower payment?
A longer term lowers the payment but raises interest and keeps you owing more than the car is worth. Sixty months suits most buyers.
How much car can I afford?
Add insurance, fuel, and maintenance to the payment and check the total against your income. A cheaper car or a bigger down payment beats a longer term.
Does my down payment really matter?
Yes: each extra thousand down cuts the loan, the payment, and the interest, and keeps you owing less than the car is worth.
Should I finance through the dealer or my bank?
Get pre-approved by your bank or credit union, then let the dealer try to beat it. Arriving with financing secured gives you negotiating power.
What is the 20/4/10 rule?
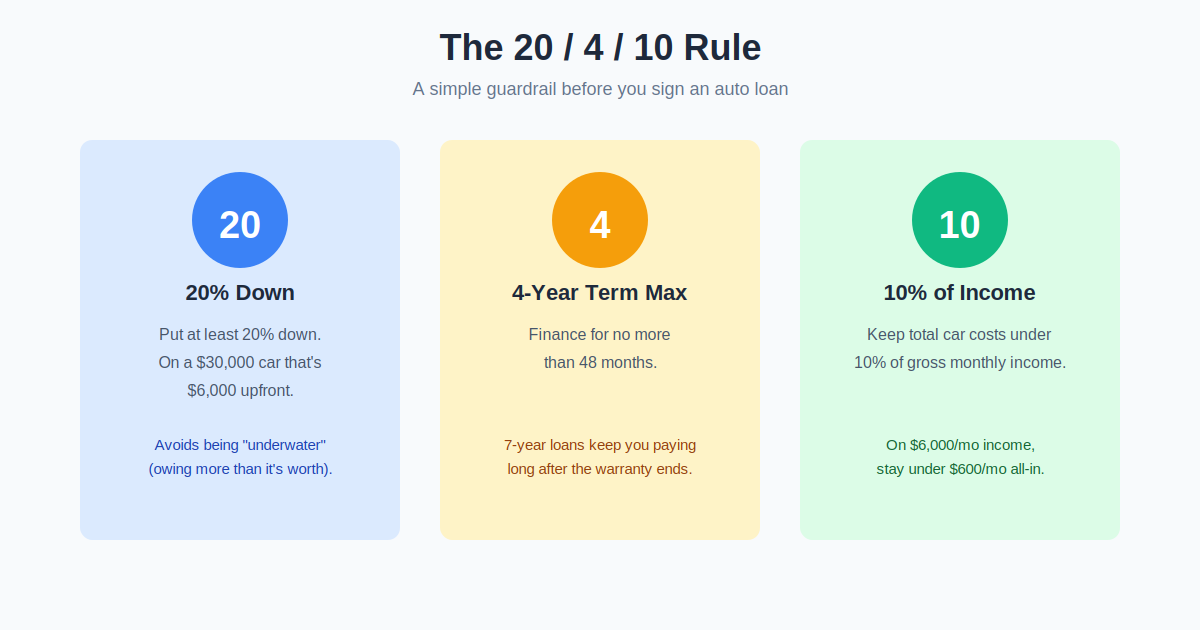
Put 20 percent down, finance for at most 4 years, and keep total car costs under 10 percent of gross income: on 5,000 dollars a month, about 500 dollars.
How is the amount I finance different from the car’s price?
The price is what the car costs; the amount financed is what you borrow after down payment and trade-in, plus financed tax and fees. Interest is charged on the amount financed.
Related Calculators
Try our Loan Calculator and Amortization Schedule Calculator for more financial planning tools.