The Hidden Clock Inside Every Business
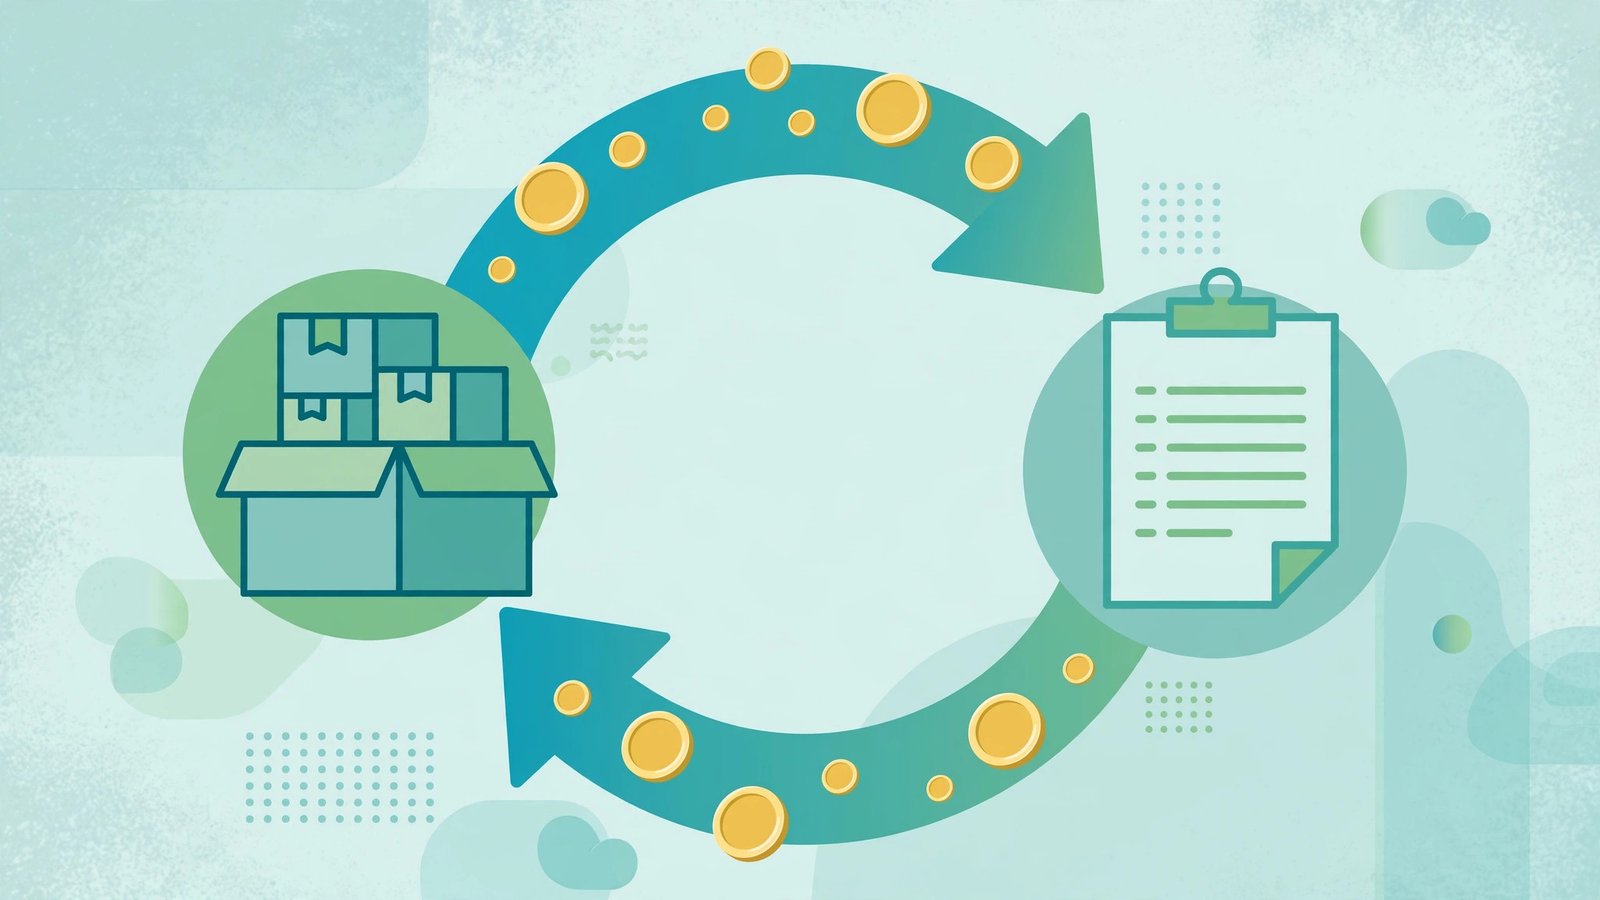
Profit on paper means little if cash is stuck: sitting in a warehouse as inventory, or sitting in a customer’s inbox as an unpaid invoice. The cash conversion cycle (CCC) — also called the cash cycle — measures exactly how many days pass between paying for what you sell and collecting the cash from selling it.
This free cash cycle calculator breaks the cycle into its three parts — DIO (days inventory outstanding), DSO (days sales outstanding), and DPO (days payable outstanding) — then combines them into your CCC. Enter revenue, cost of goods sold, and average inventory, receivable, and payable balances, and get a step-by-step breakdown with an interpretation of what your number means.
DIO · DSO · DPO → cash conversion cycle
Please enter positive revenue and COGS, non-negative average balances, and pick a period length.
A shorter cycle means cash returns faster and less outside financing is needed. Negative CCC (you collect from customers before paying suppliers) is common in fast-turnover retail. Compare against your own history and industry peers — benchmarks vary widely.
How to Use This Calculator
- Enter revenue and COGS for the period you are analyzing (annual or quarterly).
- Enter average balances — (beginning + ending) ÷ 2 for inventory, accounts receivable, and accounts payable.
- Pick the period length — 365 days for annual reports, 90 for quarterly.
- Click Calculate Cash Cycle — read DIO, DSO, DPO, your CCC, and what to do about it.
The Formulas
DSO = (Average receivables ÷ Revenue) × days
DPO = (Average payables ÷ COGS) × days
CCC = DIO + DSO − DPO
Worked example
Revenue $500,000, COGS $320,000, avg inventory $58,000, avg receivables $45,000, avg payables $38,000, annual:
- DIO = 58,000 ÷ 320,000 × 365 = 66.2 days.
- DSO = 45,000 ÷ 500,000 × 365 = 32.9 days.
- DPO = 38,000 ÷ 320,000 × 365 = 43.3 days.
- CCC = 66.2 + 32.9 − 43.3 = 55.7 days — cash is tied up nearly two months.
Who This Helps and Smart Tips
- Small business owners wondering why profits don’t match the bank balance.
- CFOs and controllers tracking working-capital efficiency quarter to quarter.
- Investors and lenders comparing operational discipline across companies.
Tips
- Most product businesses target a CCC of 30–60 days.
- Inventory (DIO) is usually the biggest lever — faster turnover beats almost everything.
- Extending DPO helps cash flow but strains supplier relationships; negotiate, don’t just pay late.
- A negative CCC (collect before you pay) is the gold standard — common in fast retail.
- Track it quarterly; a drifting cycle is an early warning of operational problems.
Which Component Is Your Real Problem?
Two businesses can share the same 55-day CCC and need opposite fixes. One is inventory-heavy: stock sits for months while customers pay on time. The other turns inventory fast but lets invoices age. Diagnose before you act — in the worked example above, DIO (66.2 days) dwarfs the other components, so inventory is where the money is trapped.
The arithmetic makes priorities concrete. Every day of DIO at this COGS level locks up $320,000 ÷ 365 ≈ $877 in stock. Cutting DIO by 20 days — through tighter purchasing, a faster-moving assortment or clearing dead lines — frees roughly $17,500 in cash. The same exercise works for DSO: each day sooner customers pay releases revenue ÷ 365.
The DPO Trap: Early-Payment Discounts
Stretching payables improves the CCC on paper, but it can be the most expensive financing you ever take. Many suppliers offer terms like 2/10 net 30 — 2% off if you pay in 10 days instead of 30. Skipping that discount to pay 20 days later costs 2% for 20 days of credit, which annualizes to roughly 44% — far more than most credit lines charge. Before extending DPO, check what you are giving up: negotiate longer terms openly, or take the discount and borrow more cheaply elsewhere.
Frequently Asked Questions
What is a good cash conversion cycle?
It depends on the industry, but most product businesses aim for 30–60 days. Service businesses with little inventory often run under 30 days, while manufacturers can legitimately run longer. Compare against your own history and direct competitors, not a universal number.
What does a negative cash conversion cycle mean?
It means you collect cash from customers before you pay suppliers — DPO exceeds DIO + DSO. This is excellent: suppliers effectively finance your growth. Fast-turnover retailers and subscription businesses achieve it most often.
How can I shorten my cash conversion cycle?
Three levers: reduce DIO by turning inventory faster, reduce DSO by invoicing promptly and following up on receivables, and extend DPO by negotiating longer supplier terms. Each day shaved off frees up roughly one day of COGS in cash.
What is the difference between CCC and operating cycle?
The operating cycle is DIO + DSO — the time from buying inventory to collecting cash. The cash conversion cycle subtracts DPO, because supplier credit offsets part of that time. CCC is the stricter measure of financing need.
Should I use 365 or 90 days?
Match your data: 365 for annual financial statements, 90 for quarterly analysis. Mixing them distorts every component, so keep the period consistent across all inputs.
Why is my CCC rising even though sales are growing?
Growth often stretches the cycle: bigger inventory bets, looser credit to win customers, and slower collections. A rising CCC during growth is normal but must be funded — watch it before it forces emergency borrowing.
Is a shorter cash conversion cycle always better?
Mostly, but not at any cost. Squeezing inventory too hard causes stockouts and lost sales; chasing customers too aggressively for faster payment can strain relationships; and stretching suppliers past agreed terms backfires in pricing and priority. The goal is an efficient cycle for your industry — not the smallest number at any price.
What is the net operating cycle?
It is another name for the same idea used in some textbooks: the operating cycle (DIO + DSO) adjusted for supplier credit by subtracting DPO. When a source says “net operating cycle,” it means the cash conversion cycle this calculator computes.
Final Thoughts
The cash conversion cycle turns vague cash-flow anxiety into a single number with three visible causes. Measure it, track it quarterly, and attack the largest component first — most businesses find inventory discipline moves the needle fastest.
Pair it with our current ratio calculator for the liquidity snapshot and our CAGR calculator for the growth picture.
Try the Cash Cycle Calculator now
Free, no signup, works on any device. Explore more financial calculators.