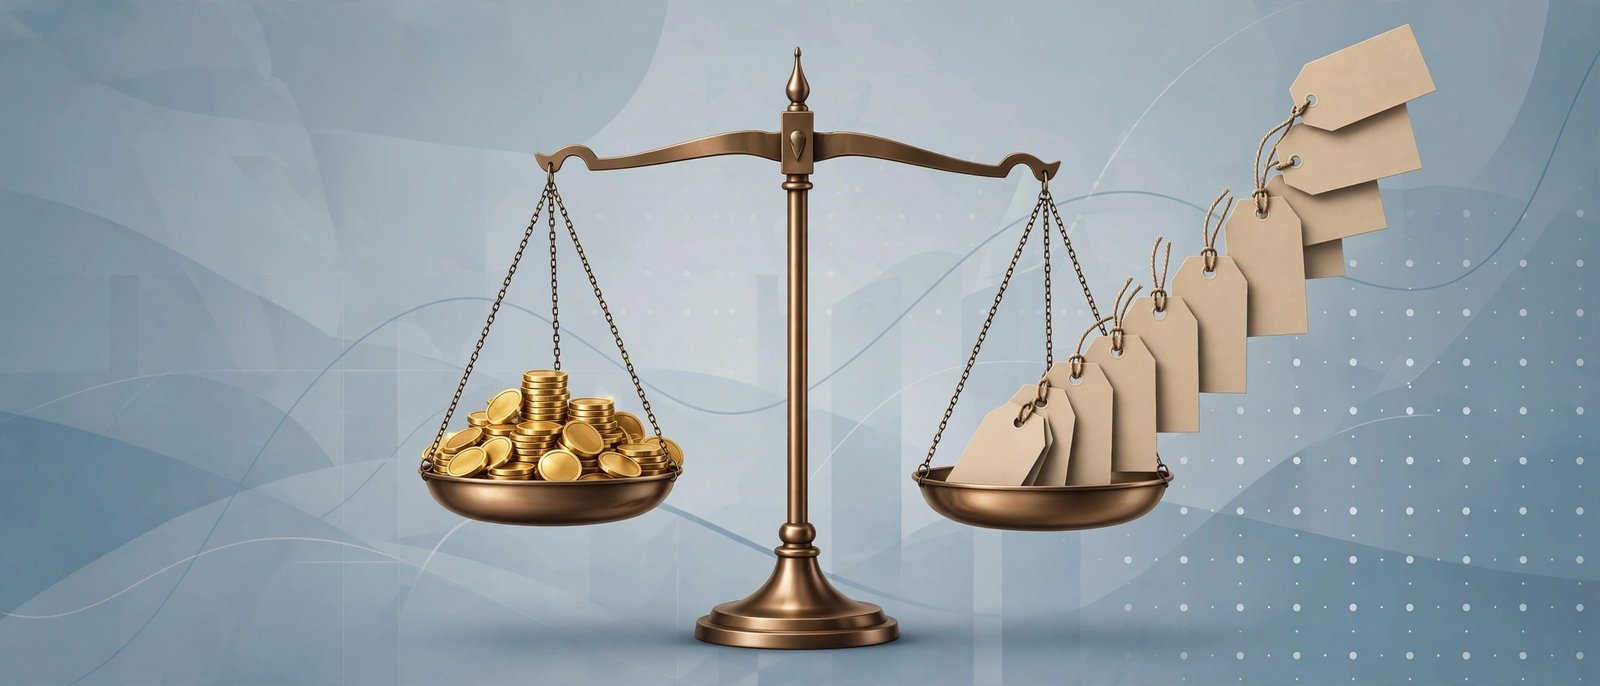
A 5% savings rate sounds good — until 3% inflation quietly eats most of it. The Fisher equation, from economist Irving Fisher (1907), is the exact link between nominal rates, real (inflation-adjusted) rates and inflation: (1 + i) = (1 + r)(1 + π).
This free Fisher equation calculator solves for any of the three variables — enter two, get the third — and shows both the exact result and the popular “i minus pi” approximation, including how far the shortcut is off.
(1 + i) = (1 + r)(1 + π) · nominal vs. real rates
Exact formula vs. the "minus" shortcut ⓘ
Please enter valid rates (greater than −100%).
Named for economist Irving Fisher (1907). Real rates drive DCF valuations, TIPS pricing and retirement planning — always compare investments in real, not nominal, terms.
How to Use This Calculator
- Choose what to solve for — real rate, nominal rate, or implied inflation.
- Enter the other two rates as percentages (e.g. 5 for 5%).
- Click Calculate for the exact Fisher result, the approximation, the approximation error in percentage points, and the full step-by-step math.
Fisher equation
Solve for r: r = (1 + i)/(1 + π) − 1
Solve for i: i = (1 + r)(1 + π) − 1
Solve for π: π = (1 + i)/(1 + r) − 1
Approximation: r ≈ i − π (ignores the r·π cross-term)
Worked example
Nominal rate 5%, inflation 3%:
Exact: r = 1.05/1.03 − 1 = 1.9417%
Approximation: 5% − 3% = 2.00%
Error: +0.0583 pp — the shortcut overstates the real return.
At 10% nominal and 8% inflation the gap widens: exact 1.85% vs. approximate 2.00%.
Why real rates run the world
- Retirement planning: a 7% portfolio return at 3% inflation is really ~3.88% of new purchasing power per year — plan withdrawals on the real number.
- Bond markets: TIPS (Treasury Inflation-Protected Securities) let you read real yields directly; the gap to nominal Treasuries is the market’s inflation forecast.
- Central banks: policy is judged on real rates — deeply negative real rates stimulate, strongly positive ones restrain.
- Rule of thumb: below ~5% inflation the shortcut is fine; above it, always use the exact formula.
Expected vs Realized: Ex Ante and Ex Post Real Rates
The Fisher equation does double duty, and the difference matters. The ex ante real rate uses expected inflation — it is the rate lenders actually build into contracts. The ex post real rate uses inflation that really happened. Borrow $10,000 at 6% expecting 2% inflation and the ex ante real rate is 1.06 ÷ 1.02 − 1 = 3.92%. If inflation actually runs at 5%, the ex post real rate is 1.06 ÷ 1.05 − 1 = 0.95%. The gap is not an abstraction: surprise inflation silently transfers purchasing power from lenders to borrowers, which is why bond markets obsess over inflation expectations. Unexpected deflation does the reverse, rewarding lenders. Try both versions of inflation in the calculator above and compare the results.
Taxes Shrink the Real Rate Again
There is one more bite to take out of the nominal rate before Fisher gets it: income tax applies to the nominal interest, not the real gain. Earn 5% nominally in a 22% tax bracket and you keep only 5 × (1 − 0.22) = 3.90% after tax. At 3% inflation, the exact Fisher real return on what is actually yours is 1.039 ÷ 1.03 − 1 = 0.87% — less than half the headline 2% approximation. Inflation is never the whole story; a tax-deferred account like a 401(k) or IRA can rescue a real return that taxes would otherwise erase.
Frequently Asked Questions
What is the Fisher equation in simple terms?
It states that $1 invested at nominal rate i grows to the same as $1 growing at real rate r with prices rising at inflation π: (1+i) = (1+r)(1+π). It separates genuine purchasing-power growth from inflation illusion.
When does the i − π approximation fail?
The shortcut ignores the r·π cross-term, which grows with the rates. At 5% nominal / 3% inflation the error is 0.06 pp (negligible); at 20% / 15% it is 0.65 pp — enough to distort investment decisions.
What is a real interest rate?
The nominal rate minus the inflation effect — what your money actually gains in purchasing power. A 5% bond yield with 3% inflation leaves you ~1.94% richer in real terms (exact Fisher).
Can real interest rates be negative?
Yes, and often are: whenever inflation exceeds the nominal rate, savers lose purchasing power. The 1970s and 2021–2022 both saw deeply negative real rates on cash and bonds.
Who was Irving Fisher?
Irving Fisher (1867–1947), the American economist who formalized the equation in 1907’s “The Rate of Interest.” He also pioneered index numbers and the quantity theory of money.
How do TIPS relate to the Fisher equation?
TIPS pay a fixed real yield plus CPI inflation — the market’s live demonstration of Fisher’s decomposition. Nominal Treasury yield minus TIPS yield ≈ expected inflation (the “breakeven” rate).
What is the Fisher effect?
The hypothesis named for the equation: nominal interest rates tend to adjust one-for-one with expected inflation, so real rates stay roughly stable over time. It is why lenders demand higher nominal rates when inflation expectations rise — and why central banks watch inflation expectations as closely as inflation itself.
How do taxes affect my real interest rate?
They shrink it twice over. Income tax hits nominal interest first — 5% at a 22% bracket leaves 3.90% — and inflation then erodes that reduced amount, leaving about 0.87% real at 3% inflation. Tax-deferred accounts protect the compounding from the first bite.
What inflation rate should I enter in the calculator?
For planning, use your expected average over the investment horizon — a long-run US average of about 2–3% is the usual choice, since it covers most peacetime stretches. To audit last year, use the actual realized rate: enter CPI inflation for the period and the calculator gives the ex post real rate you actually earned.
Final Thoughts
Every figure on this page was computed live by the tool above — try your own numbers and see how the math responds.
See through inflation illusion — solve the Fisher equation above, then explore our other free finance calculators.